After a hailstorm: your car, your claim and your repair in Tulsa
This page is for Tulsa drivers whose car took hail: dents across the hood and roof, a cracked windshield, glass on the seats. It covers the first photos, the coverage that pays, the deadlines Oklahoma law sets for your insurer, your right to choose the shop, the dent crews that show up after a storm, and what to do if the claim is denied. Shopping for a used car instead? The last section shows how to check one for old hail damage.
Sources re-checked .
Short answer
Photograph every panel, cover broken glass, and report the hail to your insurer before any permanent repair. Comprehensive coverage pays for hail, minus your deductible, and Oklahoma law sets the insurer's deadlines and lets you choose the shop. If the claim is denied or paid short, the Oklahoma Insurance Department takes complaints and offers free mediation.
Oklahoma Insurance Department: Wind and Hail; 36 O.S. §§ 1250.6-1250.8, Oklahoma Statutes Title 36 (PDF); Oklahoma Insurance Department: File an Online Complaint
The first hours: photos, broken glass and the storm date
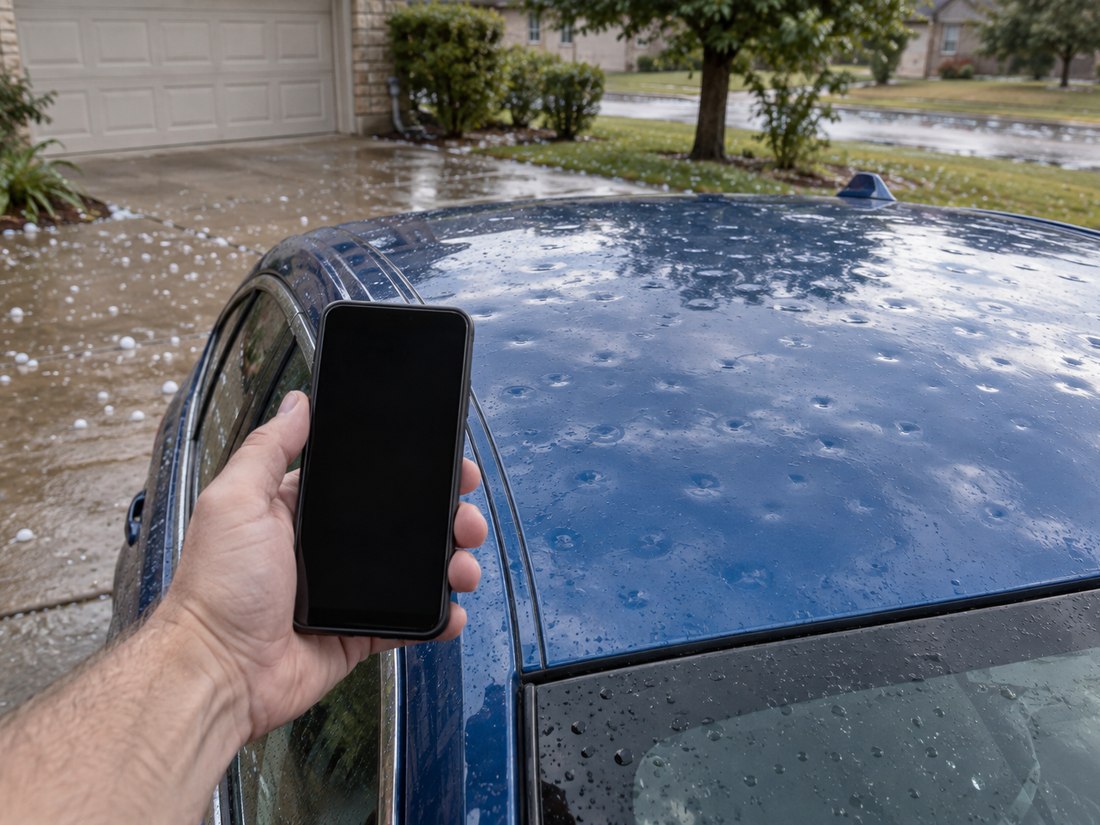
Photograph the car before anything changes. Shoot every panel, then the roof, hood and trunk lid from a low angle so the dents show, plus the glass and the inside if a window broke. After storms hit Enid in April 2026, the Oklahoma Insurance Department (OID) gave the same advice: plenty of photos or video, and keep damaged items until your insurer says you can toss them.
Stop the damage from spreading, but wait on the real repair. Tape plastic over a shattered window and keep the receipt. OID tells storm victims to hold off on permanent repairs until the insurer has inspected and agreed with them on the cost.
Note the date, the time and where the car was parked. The National Weather Service office in Tulsa takes storm reports from the public and asks for the town, county, time and date, with a photo if you have one. NWS counts a storm as severe when its hail reaches 1 inch across. Tulsa's hail history by month is on the hail season page.
Source: Oklahoma Insurance Department: guidance after the April 2026 Enid storms; NWS Tulsa: Submit a Storm Report.
Which coverage pays for hail, and what your deductible does
Hail is damage from something other than a collision, and OID puts that under comprehensive coverage. With liability alone, OID says, you may not be covered at all. The hail season page covers choosing comprehensive before a storm. Once the hail has hit, the questions are your deductible and whether to file.
The deductible is your share. Oklahoma's claims law has the insurer pay the repair cost minus the deductible in your policy, so look yours up before you call.
If the damage looks light, price it first. OID's March 2025 storm release said to get estimates before filing, and to consider not filing if the figure lands under the deductible or barely above it. OID also says Oklahoma law blocks a rate increase for an accident you did not cause, while other kinds of losses can bring surcharges. Ask your agent how your company treats a comprehensive claim.
A windshield broken by hail goes on the same claim; OID says each company decides whether glass chips are paid without a deductible. The small problems page covers a crack on its own.
Source: Oklahoma Insurance Department: Wind and Hail; Oklahoma Insurance Department: How to File a Claim; Oklahoma Insurance Department: Choosing your Automobile Insurance Policy; Oklahoma Insurance Department: guidance after the March 2025 fires and high winds; 36 O.S. § 1250.8(H), Oklahoma Statutes Title 36 (PDF).
Filing the claim: Oklahoma's deadlines for you and the insurer
Report the hail as soon as you find it. Calling your agent counts, because Oklahoma law treats notice to an agent as notice to the insurer. Log each contact: date, name, what was said.
Your own deadline is in your policy, under reporting a loss. Oklahoma's unfair claims law lists, among unfair practices, holding you to a notice deadline the policy does not contain, unless the late notice hurt the insurer's rights. The 24-month hail window in that same paragraph covers roofs, not cars.
| What the insurer must do | Deadline | Title 36 |
|---|---|---|
| Acknowledge your claim, unless it pays first | 30 days after your notice | § 1250.6(A) |
| Provide claim forms, instructions and reasonable help, and proof-of-loss forms if you ask in writing | Promptly | §§ 1250.6(B), 3629(A) |
| Accept or deny the claim, or say it needs to investigate further | 60 days after it receives your proof of loss | § 1250.7(A) |
| Send a written settlement offer or rejection | 60 days after it receives your proof of loss | § 3629(B) |
| Finish investigating | 60 days; 120 at most, unless it has specific grounds to investigate fraud or arson | § 1250.7(C) |
When the Governor declares a weather-related catastrophe or a major natural disaster, the Insurance Commissioner may add 20 days to the decision and investigation limits. A denial must be in writing and must cite the policy provision, condition or exclusion behind it.
Source: Oklahoma Insurance Department: Wind and Hail; 36 O.S. §§ 1250.5(7), 1250.6, 1250.7 and 3629, Oklahoma Statutes Title 36 (PDF).
The adjuster's inspection and the estimate
The insurer has a right to inspect before cleanup or repair, OID's March 2025 release says. The same unfair-practices list protects you: it includes denying a claim because you did not show the property, unless the insurer can prove it asked and you refused without good reason.
Ask the adjuster for identification, and confirm the license by calling OID or checking its website. After Tulsa's Father's Day weekend storms in 2023, the commissioner issued an emergency order letting insurers use out-of-state adjusters and temporarily waiving local licensing rules. The insurer pays its adjuster, and OID says an adjuster should not ask you for money.
Read the estimate line by line. Oklahoma law says the insurer's figure must be one that can reasonably be expected to cover a satisfactory repair, and you get a copy. Cuts for betterment or depreciation must be itemized in dollars. If you take cash instead of a repair, outside a total loss, the insurer cannot pay less than the repair would cost unless you agree.
If the insurer totals the car, the insurance page explains that settlement, and the hail, flood and salvage page covers the title.
Source: Oklahoma Insurance Department: guidance after the March 2025 fires and high winds; Oklahoma Insurance Department: Insurance Tips After the Storm (July 2023, Tulsa); Oklahoma Insurance Department: After the Disaster; 36 O.S. §§ 1250.5(6) and 1250.8(F), (G), (I), Oklahoma Statutes Title 36 (PDF).
Can the insurer make you use its body shop?
No. The statute is plain: “An insurer or its representative shall not require a claimant to obtain motor vehicle repairs at a specific repair facility.” The next sentence says the same about glass shops. If you ask, the insurer may give you names of nearby shops, and it may not make you travel an unreasonable distance for an estimate or a repair.
Picking the shop does not bind the insurer to the shop's price. Unless you take cash, the law ties payment to a competitive price, set by the insurer's market surveys or, if you choose, by competitive bids you collect, with reasonable deviation allowed. Get your shop's written estimate to the adjuster early. At pickup, the shop must give you an itemized, priced repair statement. Keep it with the title for a future buyer.
Your shop may propose paintless dent repair on some panels and replacement on others. OID's hail guidance does not compare the two, and no Oklahoma statute chooses between them. The test stays the same: enough money for a satisfactory repair. If your shop disagrees with the adjuster's method for a panel, ask it to explain why in writing for the adjuster. If that fails, use the complaint steps below.
Source: 36 O.S. § 1250.8(D), (F) and (H), Oklahoma Statutes Title 36 (PDF); Oklahoma Insurance Department: Wind and Hail.
Out-of-town dent crews and door-to-door offers
Writing about Tulsa's 2023 storm recovery, Insurance Commissioner Glen Mulready warned that bad actors follow bad storms. Attorney General Gentner Drummond's office says contractor fraud rises for weeks and months after a storm or tornado. His tips were written for home repairs, but this one fits a dent shop: “Established local businesses with a physical address and proven track record are typically more trustworthy than fly-by-night operators who appear after a disaster.”
Tulsa Police's Financial Crimes Unit sent its own alert after the June 2023 storms. Find a repair business yourself instead of hiring whoever knocks, research it first, and do not pay in full before the work is done. On reviews, the unit warned: “Do not blindly trust internet 5 star reviews, as these can be manipulated by the scammer.”
OID adds: check references (it notes the Better Business Bureau collects contractor complaints), never sign a contract with blank spaces, and never sign your insurance payment over to a repairer. OID also warns against contractors who offer to waive a deductible. Oklahoma's ban on that, 59 O.S. § 1151.30, is written for roofing contractors, so ask your insurer before accepting such an offer from a dent shop.
The FTC's Cooling-Off Rule gives you until midnight of the third business day to cancel a door-to-door sale: $25 or more at your home, or $130 or more elsewhere away from the seller's place of business, such as a hotel or motel room rented short term. It does not apply when you invited the business to your home to repair your property.
To check a business or complain, call the Attorney General's Consumer Protection Unit at 1-833-681-1895. Tulsa Police asks storm-scam victims to file an online police report. Suspected insurance fraud goes to OID's Anti-Fraud Unit, which has offices in Oklahoma City and Tulsa: fraud.stoppers@oid.ok.gov.
Source: Oklahoma Insurance Department: Insurance Tips After the Storm (July 2023, Tulsa); Oklahoma Attorney General: Drummond warns of contractor fraud after severe weather (March 4, 2025); Tulsa Police: Scam Alert, Beware Tulsa storm debris scammers (June 20, 2023); Oklahoma Insurance Department: guidance after the April 2026 Enid storms; Oklahoma Insurance Department: After the Disaster; 59 O.S. § 1151.30, Oklahoma Statutes Title 59 (PDF); FTC Cooling-Off Rule, 16 CFR Part 429 (eCFR); Oklahoma Insurance Department: Anti-Fraud Unit.
Claim denied or paid short: where to take it
Start with the denial letter. It must be in writing and name the policy language behind it, so set that language beside your policy and ask the insurer to explain in writing anything unclear. Commissioner Mulready's May 2026 column on claim disputes reminds readers that a denial is not always final.
If the company will not move, file a request for assistance with OID at oid.ok.gov/complaint, or print the form and mail or fax it. Attach the policy, estimates, letters and your call log. An analyst acknowledges it and asks the company for its side. OID's complaint page states: “By law, the company has twenty (20) days from receipt of our letter to respond.”
OID cannot order a company to pay, set the value of a claim, or act as your adjuster. What a complaint does get you is a fresh, objective evaluation and a check on whether the company followed Oklahoma law. If the complaint does not settle it, OID may offer EAGLE mediation: free, voluntary for both sides, and run by mediators the Oklahoma Supreme Court approves. If mediation ends without a deal, you can still sue.
OID's Tulsa office: Meridian Tower, 5100 E. Skelly Drive, Suite 110, Tulsa, OK 74135, (918) 295-3700, Monday through Friday, 8 a.m. to 5 p.m. except state holidays. Statewide: (800) 522-0071.
Source: Oklahoma Insurance Department: File an Online Complaint; Oklahoma Insurance Department: What Every Oklahoman Should Know About Insurance Claim Disputes (May 2026); Oklahoma Insurance Department: EAGLE Mediation Program; Oklahoma Insurance Department: Contact Us; 36 O.S. § 1250.7(A), Oklahoma Statutes Title 36 (PDF).
Buying used in Tulsa: checking a car for old hail damage
A clean Oklahoma title does not prove a car escaped hail. Service Oklahoma has insurers leave cosmetic hail out of the damage figure that sets the title type; the hail, flood and salvage page explains. Check the car and its claim history instead.
- Pull an NMVTIS report. It shows title brands, any insurer finding of salvage or total loss, and any sale to a junk or salvage yard. Its gap matters for hail: the Justice Department says serious past damage may be missing if no insurer totaled the car and no state branded the title.
- Try NICB's free database. The Justice Department's buying tips point to the National Insurance Crime Bureau's free VIN search.
- Ask the seller about hail claims. Oklahoma allows a cash settlement, so a paid claim does not prove a repair. If the car was fixed, ask for the insurer's estimate and the shop's itemized repair statement.
- Book an independent inspection. The NMVTIS disclaimer says a history report is no substitute for one. Ask the inspector to check the roof, hood and trunk lid for dents and body repair.
Source: NMVTIS Consumer Access Product Disclaimer, U.S. Department of Justice (PDF); NMVTIS: information for consumers; NMVTIS: used car buying tips; Service Oklahoma Form 780-B, page 2 (PDF); 36 O.S. § 1250.8(H) and (I), Oklahoma Statutes Title 36 (PDF).
Questions Tulsa drivers ask after hail
Do I have to fix the dents if the insurer pays me?
Oklahoma's claims law allows cash in place of a repair, and outside a total loss the cash cannot be less than the repair cost unless you agree. Check your policy, and your loan agreement if a lender holds the title.
A dent company offered to pay my deductible. Is that allowed?
Oklahoma's explicit ban, 59 O.S. § 1151.30, covers roofing contractors. For your car, ask your insurer how it treats the offer before you sign, and keep every estimate and invoice.
Will a hail claim raise my rates?
OID says Oklahoma bars a rate increase for an accident you did not cause, but other kinds of losses can bring surcharges. Ask your agent before you file a small claim.
If the insurer totals it, or you would rather not repair
If the insurer totals the car and you keep it, or the dents are not worth fixing to you, you can sell it as it is. Call (539) 271-2021 or use the sell-it-to-us form. Anywhere in Tulsa, we buy some cars ourselves and pay for them by check. When a car is not one we can buy, we tell you on the call and point you to a partner's free online offer.
More on selling a car in Tulsa
- PaperworkWhat you sign, who notarizes it, the two-day deadline, and which counter in Tulsa takes it.
- Cash for carsMoney for a running, dead or junk car anywhere in Tulsa: our offer or the partner route, paid by check.
- Bill of saleWhen Oklahoma needs a bill of sale, whether it is notarized, and what goes on it.
- Repair or sellCompare repair costs with the extra sale proceeds, then check Oklahoma's salvage and rebuilt title rules.
- After you sellPlate off, the two-day filing, insurance, PikePass, and what to do if a ticket arrives for a car you sold.
- Title problemsLost the title, a lien still on record, the owner has died, or the title is from another state.